Derivatives & Hedging Trades
Three hedged positions run and logged in a paper-trading account: a daily delta hedge of a short SPX put, a MicroStrategy-versus-bitcoin-ETF pair trade, and an inverse-ETF hedge.
- Role
- Trader and analyst
- Context
- Fall 2025 · FIN 330 Derivatives
- Team
- Individual paper-trading account
- Deliverable
- Paper-trading logs + brief
Summary
The question
Each trade tested a different way of removing unwanted risk: delta to neutralize index direction on a short option, beta to size a relative-value pair, and dollar-matching to test how cleanly a −1× ETF offsets its benchmark.
What I did
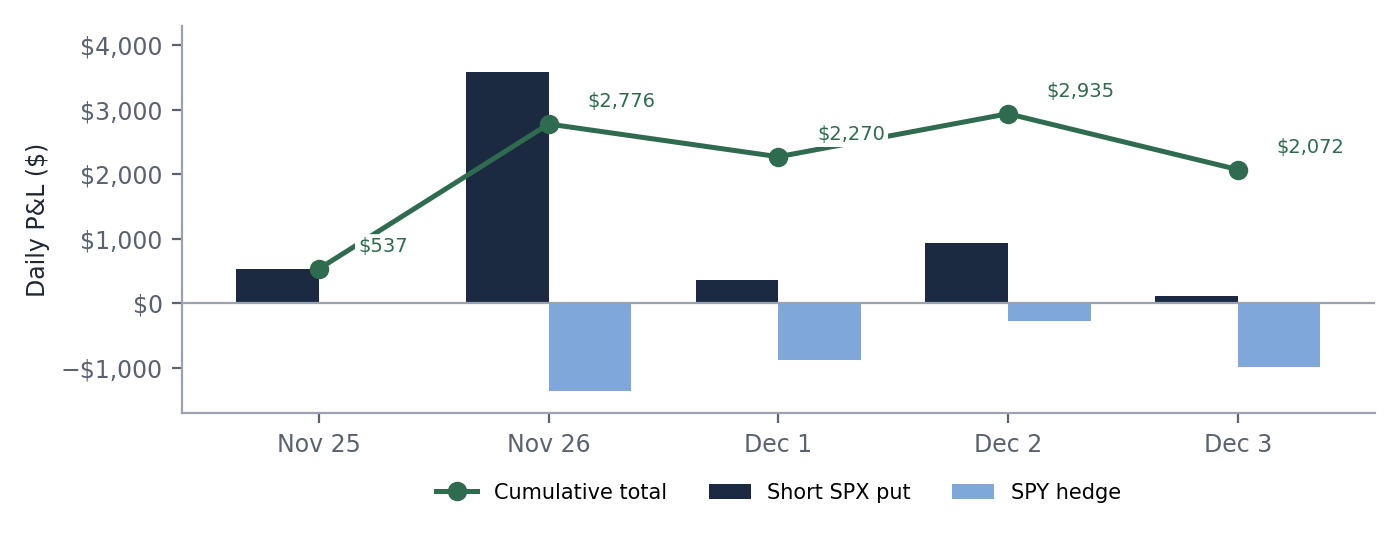
- Sold one SPX Dec-2025 6600 put and re-hedged daily with short SPY sized at INT(put delta × 100 × 10), trimming the hedge from 344 to 164 shares as the put’s delta fell.
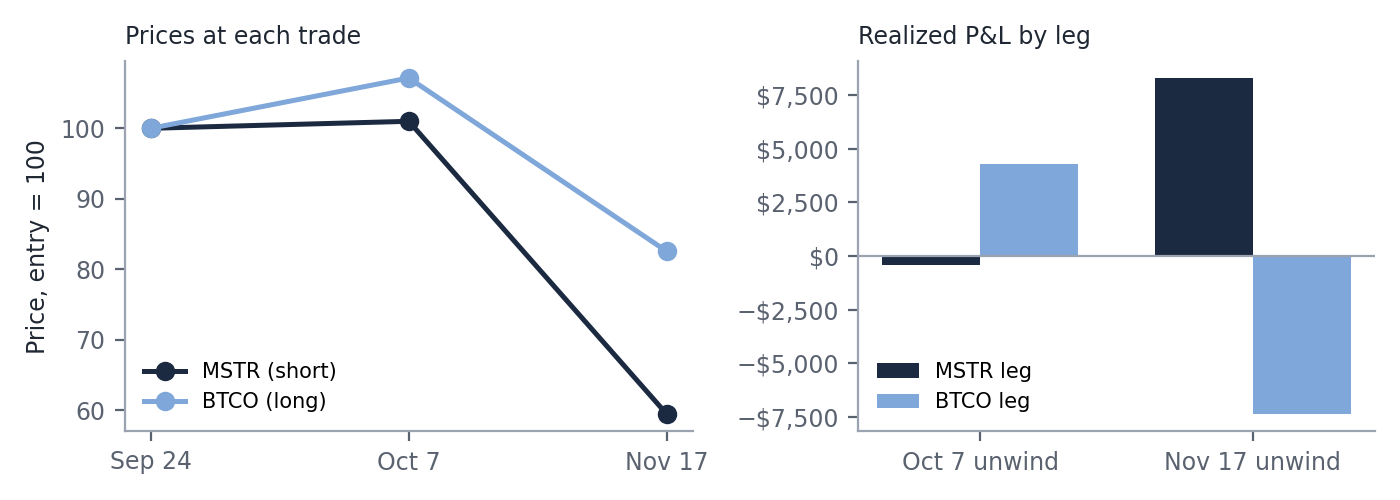
- Shorted 120 MSTR against 528 BTCO (≈1.5× the MSTR notional to reflect MicroStrategy’s higher bitcoin beta), then unwound the pair in two halves.
- Bought dollar-matched SH and SPY (~$330K per leg) and measured the one-day tracking gap, then rebuilt every log in one workbook with live formulas.
What it showed
Sizing drove every result. The delta hedge removed direction but not jump risk: the biggest single-day move came from a drop the prior day’s delta could not anticipate, which is why gamma and rebalancing frequency belong in the plan.
From the work
A delta hedge removes direction, not risk. The largest single-day P&L came from a jump the hedge ratio could not anticipate, which is why rebalancing frequency, gamma and vega belong in the plan, not just the starting delta.
Trading brief
Charts and slides
| Trade | Structure | Window | Net P&L |
|---|---|---|---|
| Delta hedge | Short 1 SPX Dec-2025 6600 put; SPY re-hedged daily | Nov 24 – Dec 3, 2025 | +$2,072.02 |
| Pair trade | Short 120 MSTR vs. long 528 BTCO (≈1.5× notional) | Sep 24 – Nov 17, 2025 | +$4,809.96 |
| Inverse-ETF hedge | Long 8,758 SH vs. long 500 SPY, dollar-matched | 1 day | +$485.80 |
| Combined | +$7,367.78 |
Paper-trading account used for coursework; no real capital.
In my words
This derivatives project gave me the chance to move beyond textbook payoffs and see how hedges behave as prices, volatility, and correlations change. The daily delta hedge was especially useful because it made option risk feel dynamic rather than static. It was one of the projects that made derivatives much more intuitive for me.
Documents
If the preview does not load on your device, open the PDF in a new tab.
- Trading briefPDF · 2 pages · Excel logs available
Paper-trading account used for coursework; no real capital. Account identifiers removed from all files.