Social Inflation & Casualty Risk
Research on how nuclear verdicts, third-party litigation funding, attorney advertising, and eroding damage caps push casualty claim costs above economic inflation.
- Role
- Researcher and presenter
- Context
- November 2024 · Gen Bus 360 field presentation
- Team
- Individual research
- Deliverable
- Field presentation + research brief
Summary
The question
Social inflation is widely discussed but difficult to isolate. The project needed to define the mechanism clearly enough to explain why liability outcomes were worsening and what that meant for insurers and the people who buy insurance.
What I did
- Started from nuclear verdicts, including the McDonald’s hot-coffee case, and traced how jury attitudes toward corporations changed claim outcomes.
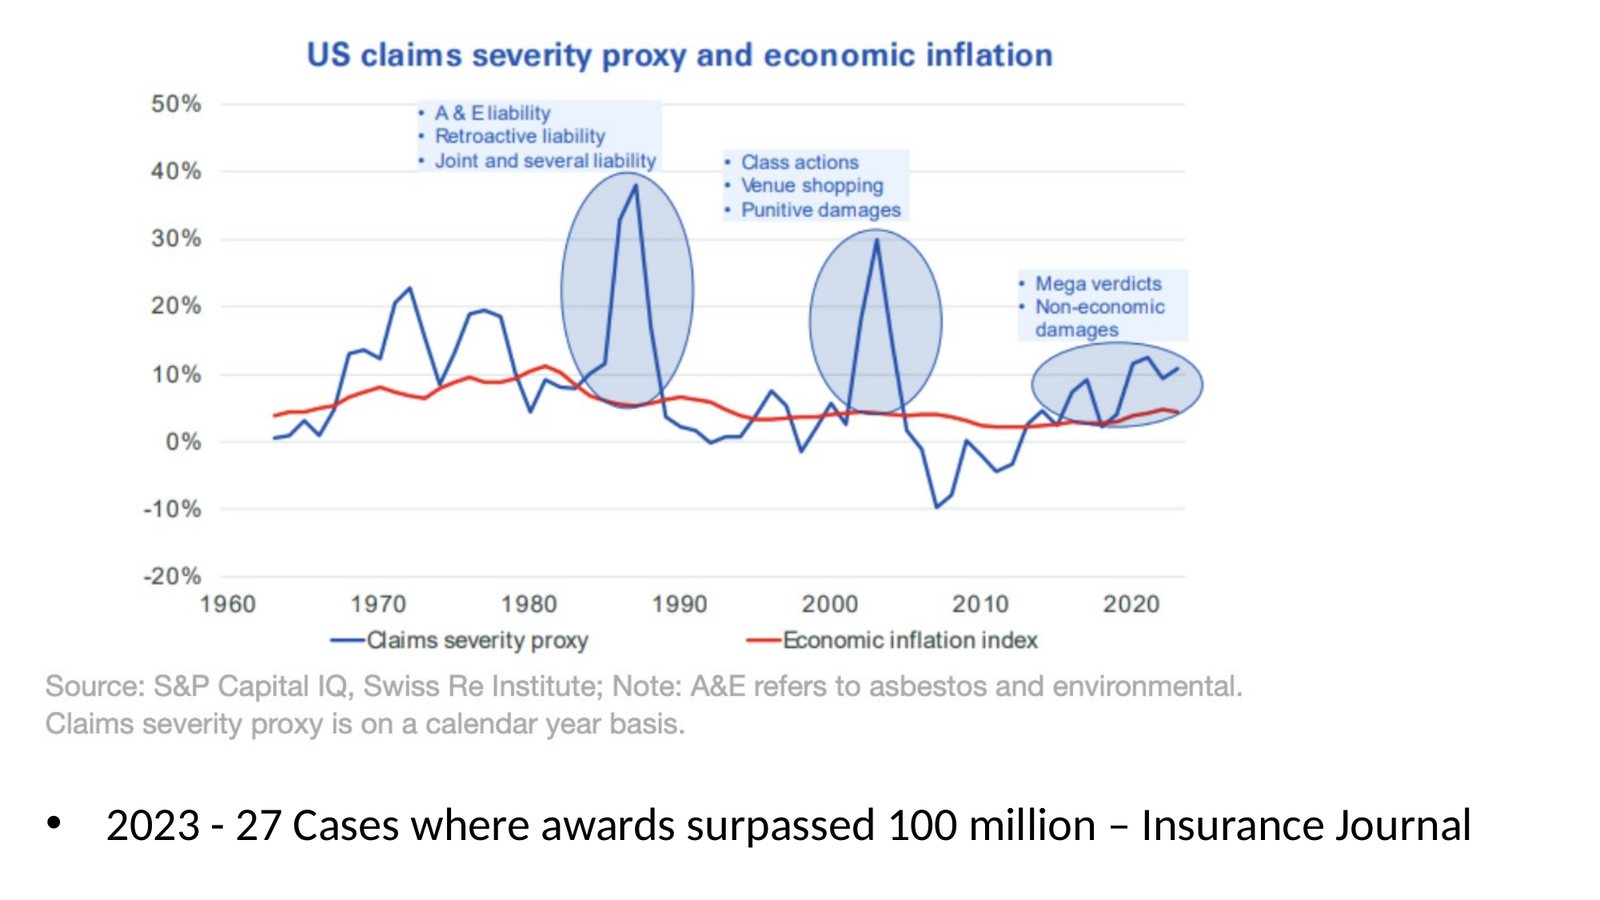
- Showed claim severity rising well above economic inflation, including 27 awards above $100M in 2023 and an estimated $30B added to commercial auto costs.
- Explained the drivers (third-party litigation funding, contingency fees, attorney advertising, and eroding damage caps) and their effect on insurer profitability and consumer premiums.
What it showed
An emerging risk becomes actionable when its causes, its financial path to the insurer, and the resulting cost to customers are shown together.
From the work
The useful question is not whether social inflation exists in the abstract. It is which forces are changing expected severity, how quickly those changes reach the portfolio, and which management levers can reduce the exposure.
Research brief
Charts and slides
In my words
I chose social inflation as a presentation topic largely because I found it entertaining and unusually relevant to the insurance industry. The research let me dig into nuclear verdicts, litigation funding, attorney advertising, and other forces that can push casualty losses beyond normal economic inflation. It was a topic I genuinely enjoyed learning and presenting.
Documents
- Field presentationPDF · 8 slides · PowerPoint available
- Research briefPDF · 3 pages